
Stone coated metal roofing landed cost should include the confirmed goods and all relevant costs to a defined delivery point. Start with a current supplier quotation, then add charges that the quotation does not already include. Use consistent quantities and currency, and keep uncertain inputs visible.
The delivery point matters. A shipment budget ending at the destination port differs from one ending at the buyer’s warehouse. Define that boundary before comparing suppliers or calculating a cost per covered area. Otherwise, two apparently precise totals may describe different purchasing scopes.
This guide provides a worksheet method and a clearly hypothetical example. It does not supply current freight rates, product prices, customs classifications, or destination tax rates. Those inputs need confirmation for the actual shipment and importing jurisdiction.
Define the Shipment and the Cost Boundary
Start with the exact order being evaluated
List the field tiles, accessories, packaging, and any separately purchased items. Identify product codes, quantities, and specification revisions. Use the same order information for the supplier, freight forwarder, and customs adviser. Estimates based on different product lists cannot form one reliable landed-cost calculation.
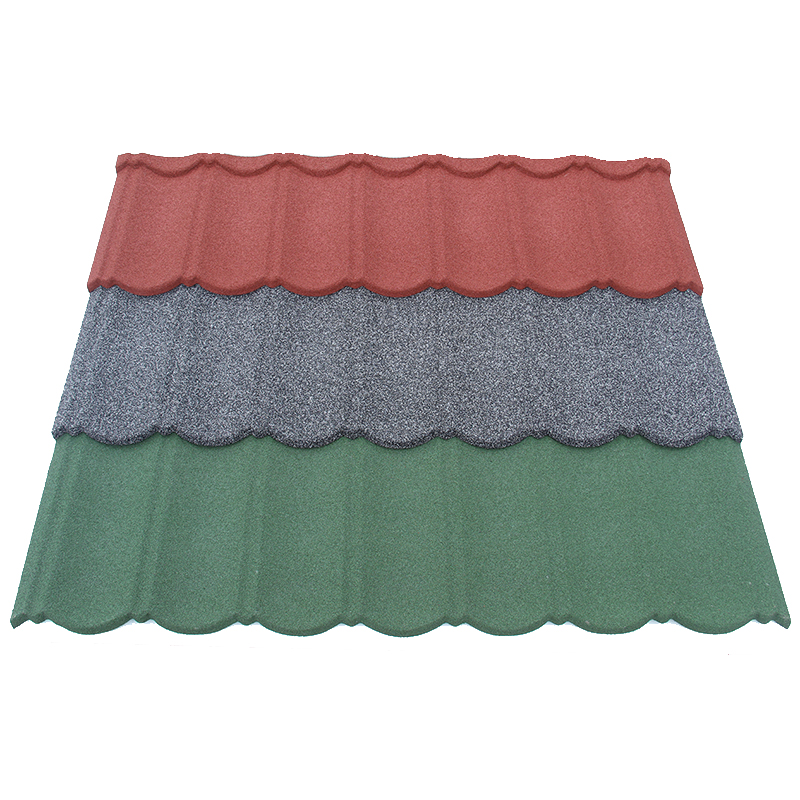
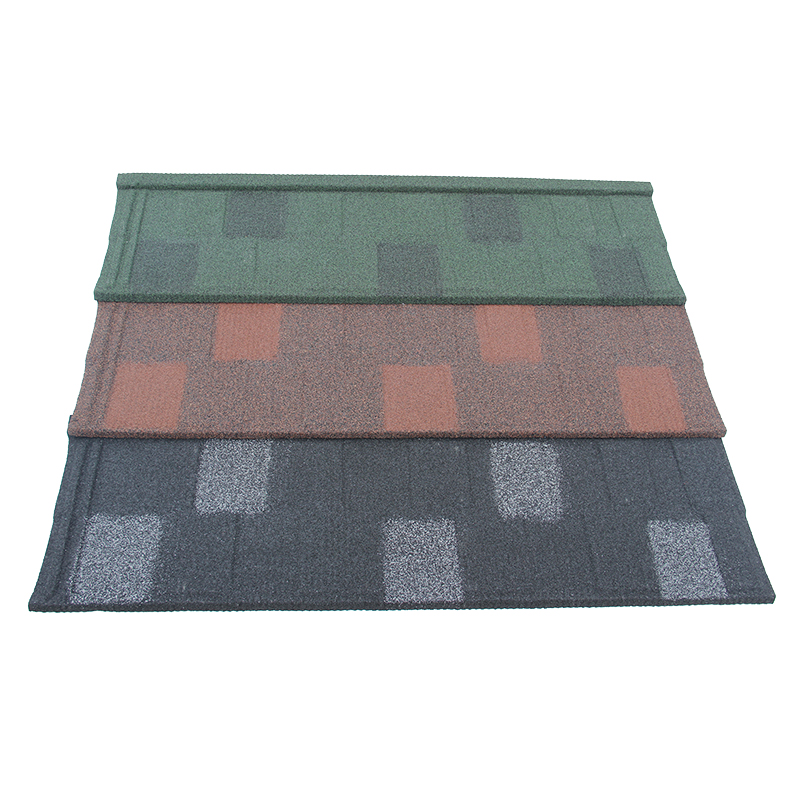
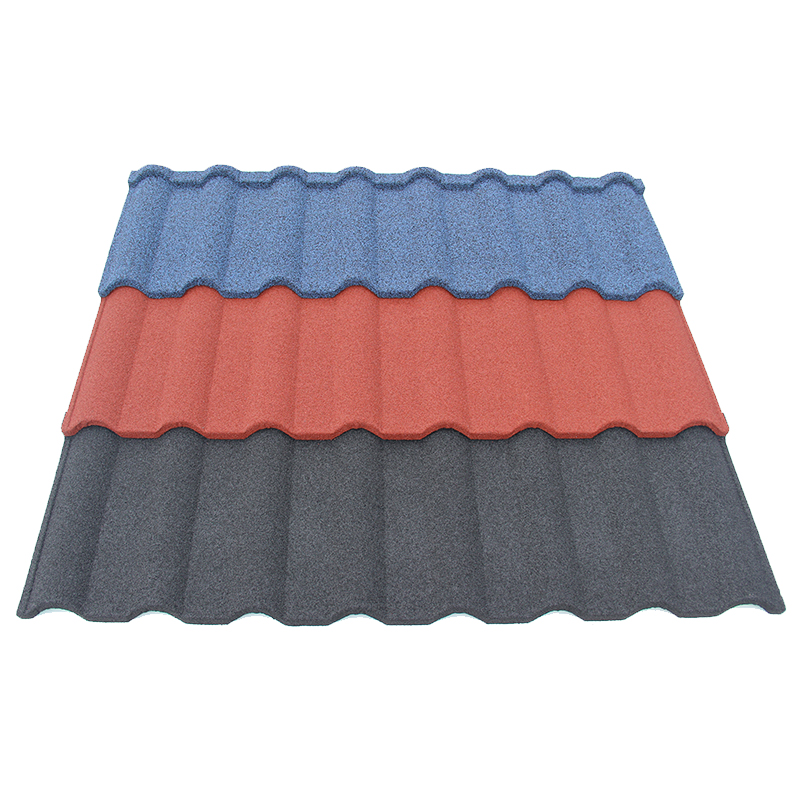
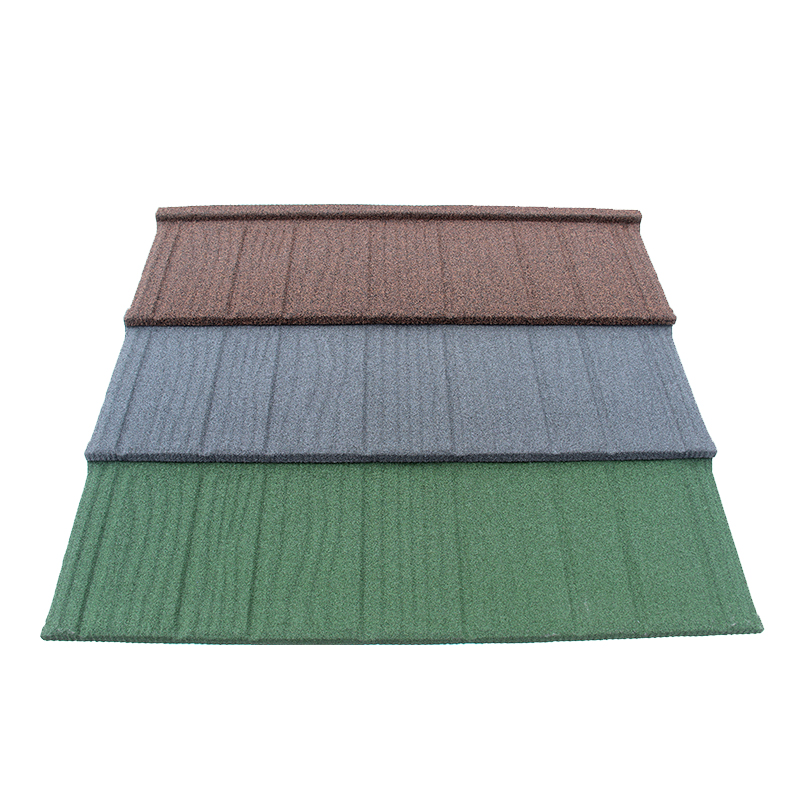
Confirm the effective coverage for each field tile. Keep it separate from nominal dimensions and packing counts. A Bond Tile order needs its own confirmed coverage basis. Do not borrow the coverage or packing assumptions of another profile merely because the products look similar.
Record the proposed origin, destination, shipment mode, and delivery boundary. Ask the logistics provider to identify any route assumptions. State whether the calculation ends at a port, terminal, warehouse, or project location. Include onward costs only where they belong within the defined boundary.
The International Trade Administration explains landed cost as the product cost plus relevant shipment charges, duties, taxes, and other fees. That provides a useful checklist, but your worksheet still needs its own boundary. Do not assume every supplier uses the term identically.
Identify what the supplier price already includes
Record the agreed trade term, named location, and rule version where applicable. Ask the supplier to identify included services and exclusions. A freight amount already included in an offer should not be added again. The worksheet should show the inclusion clearly, rather than bury it inside an unexplained total.
Obtain a separate breakdown where an offer combines goods and transport. If the supplier cannot separate every component, mark the bundled amount and its stated scope. Compare alternative offers at the same delivery boundary. A larger supplier total may include costs absent from the competing quotation.
Identify separately charged sampling, inspection, artwork, or development where relevant. Decide which costs belong to this shipment and which require another accounting treatment. Record that decision consistently across the comparison. Ask the appropriate financial adviser when a cost allocation or tax treatment requires professional judgment.
Company background helps identify the supply relationship behind the offer. With JCROOF, connect the proposed products to a written quotation and confirmed packing information. Ask for current order-specific details. A company introduction cannot determine the shipment’s freight, destination charges, or tax treatment.
Build the Worksheet from Confirmed Cost Lines
Separate goods, transport, and destination services
Begin with the invoice scope for the accepted goods and packaging. Add origin or export services only when they are not already included. Record the party providing each estimate and the quotation date. Keep assumptions beside the amount, so later reviewers can see what the figure actually covers.
Add the relevant main transport and insurance costs without duplication. Ask whether the quoted route and equipment match the actual packing plan. Confirm the charge basis and validity. A transport estimate for different cargo weight or package dimensions may not remain applicable after the order is finalized.
Request destination handling, clearance service, and inland delivery estimates from the appropriate providers. Ask for inclusions and exclusions in writing. Mark possible conditional charges separately from the expected base case. Do not present a potential storage or delay charge as an unavoidable cost for every shipment.
Use one currency for the comparison and record the conversion basis. Distinguish a planning exchange rate from an actual payment rate. Update the worksheet when significant input quotations change. A consistent method is more useful than a precise-looking total assembled from unrelated dates and currencies.
Confirm customs and tax inputs for the destination
Ask a qualified customs adviser to confirm the product classification and applicable requirements. Provide the actual material description, product information, origin, and shipment details. Do not guess a customs code from a short marketplace title. The classification should reflect the goods being imported and the destination’s applicable rules.
The International Trade Administration’s tariff guidance notes that customs authorities make the final determination. It also distinguishes duties from other taxes and fees. Use current destination-specific advice rather than applying a generic percentage from another country’s roofing import example.
Ask which value forms the basis for each assessment. Different charges may use different calculation methods or bases. Have the adviser review the worksheet where those rules affect the result. Do not assume the same percentage can be applied to the supplier invoice for every destination and every charge.
Separate cash required at import from any later accounting treatment. A business may need to distinguish taxes paid from amounts recoverable under applicable rules. Ask its accountant to confirm the treatment. Keep that adjustment visible instead of silently reducing the cash budget needed to receive the goods.
Calculate the Total and Choose a Useful Allocation Basis
Work through a transparent hypothetical example
The following figures are fictional and illustrate the worksheet structure only. They are not current quotations or a customs calculation. Assume the goods invoice includes the agreed roofing products and their packaging. Assume every additional cost line is separate and has not already been included elsewhere.
| Cost line | Hypothetical amount in USD | Assumption |
|---|---|---|
| Goods and packaging | 10,000 | Complete agreed invoice scope |
| Main freight | 1,200 | Separately charged transport |
| Cargo insurance | 100 | Separately charged agreed coverage |
| Destination handling | 500 | Defined provider estimate |
| Clearance service | 200 | Brokerage service only |
| Inland delivery | 400 | Delivery to the defined warehouse |
| Duty allowance | 800 | Fictional estimate, not a stated tariff |
| Import tax allowance | 1,300 | Fictional estimate, not a stated tax rate |
| Total cash budget | 14,500 | Sum of the listed non-duplicated amounts |
The arithmetic is straightforward, but the input definitions determine whether it is useful. Check that clearance service does not already include a charge listed elsewhere. Confirm whether destination handling covers the services assumed. Replace each fictional value with current, shipment-specific information before making a purchasing decision.
Suppose the shipment contains field tiles representing 2,000 square meters of confirmed effective coverage. Dividing the hypothetical total by that area gives USD 7.25 per square meter. This is a shipment cost allocation, including its listed scope. It is not a quoted factory price for a single tile product.
If the invoice also contains accessories, that area-based allocation includes their cost. Label it as a roofing package allocation rather than a field tile price. For mixed orders, another allocation method may be more useful. Choose the method according to the decision being made and document its limits.
Keep different products and allowances identifiable
Separate line items when comparing different profiles or finishes. Confirm their coverage and packing information independently. Allocating every shipment cost equally per piece may distort the result when products differ significantly. Ask the relevant team to agree a consistent method for the comparison or inventory purpose.
Keep transport damage, project cutting allowances, and spare stock separate. They answer different questions and should not be combined into one unexplained deduction. Use the estimator’s requirements for the project quantity. Use receiving and inspection records when reviewing the quantity actually available after delivery.
State which quantity forms the denominator. Ordered coverage, received coverage, and accepted usable coverage can differ. An area cost calculated using one basis should not be compared directly with another basis without explanation. This matters when assessing suppliers, warehouse stock, or the cost of a particular project package.
Review uncertain inputs with explicit scenarios. Change only identified assumptions, such as a pending freight offer or unresolved destination charge. Do not add a universal contingency percentage and call it a confirmed cost. Keep the expected case and alternative cases separate for the decision-maker.
Update the Estimate as the Shipment Develops
Reconfirm important inputs before committing
Check supplier offer validity and the current order revision. Confirm packing quantities, dimensions, and weights with the logistics team. Ask providers to update quotations where the cargo or route has changed. A small product change can alter the shipment assumptions behind an earlier cost estimate.
Review the named delivery arrangement and every excluded charge again. Confirm who will arrange each service and who receives the invoice. Obtain appropriate advice where commercial or customs responsibilities need interpretation. The worksheet should support those discussions without pretending to replace the underlying agreements.
Link the estimate to identifiable quotations and supporting records. Store the provider, date, scope, currency, and validity for each important input. Mark unresolved values clearly. Purchasing, finance, and logistics staff can then assess the same estimate. They should not need the author’s memory to interpret it.
Approve the order using the current evidence and stated assumptions. Record the decision date and any conditions still requiring confirmation. Update the estimate when those conditions are resolved. Do not continue using an earlier total after the actual shipment scope becomes materially different.
Reconcile actual charges after delivery
Compare invoices with the estimate once the shipment has arrived. Investigate differences in goods, freight, destination services, and customs-related amounts. Record whether the cause was a changed scope, an inaccurate estimate, or a conditional event. The explanation is more useful than simply labeling the shipment over budget.
Connect receiving records to the product quantities used in the calculation. Separate shortages, damage, and accepted deviations from the original order. Review the relevant cost allocation where quantities differ. Keep any later supplier settlement identifiable instead of rewriting the original purchasing estimate without explanation.
Use the reconciliation to improve the next shipment’s worksheet. Retain current provider information and identify recurring exclusions that need earlier clarification. Reconfirm variable charges for each new order. A successful past calculation does not guarantee the same freight, tax, or destination costs later.
Reliable landed-cost calculation begins with a defined order and delivery boundary. Add non-duplicated, supported cost lines, then divide by a clearly identified quantity basis. Label estimates and hypothetical scenarios honestly. Reconcile them with actual records so future purchasing decisions improve with evidence.